
Do I Need a Financial Advisor Quiz
How the Scales are Structured
Who Usually Takes This Test?
See How You Compare
Below is a preview of how scores are typically distributed across each scale.
Example Questions From the Test
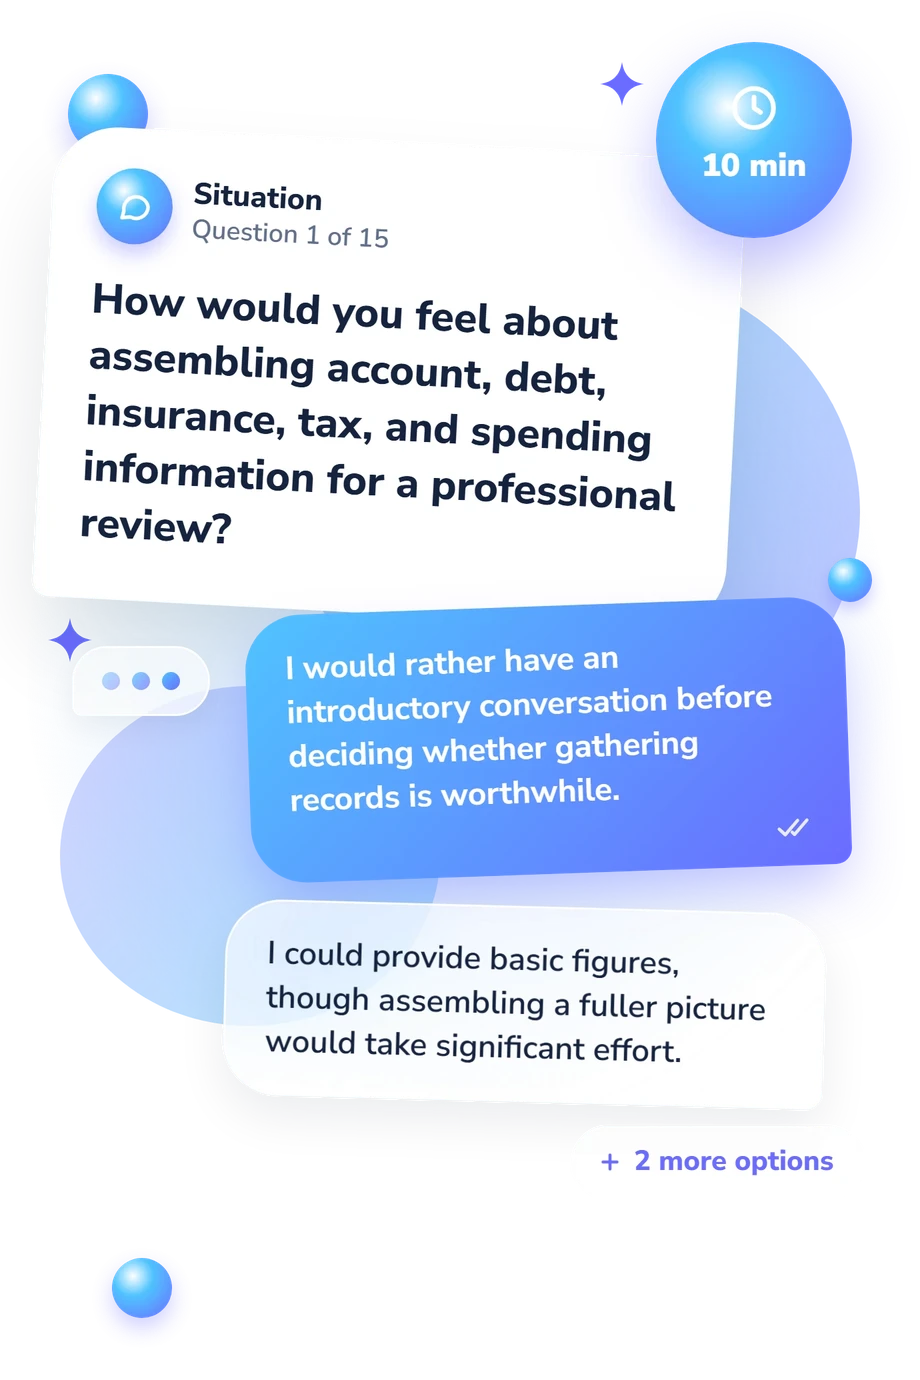
- I would rather have an introductory conversation before deciding whether gathering records is worthwhile.
- I could provide basic figures, though assembling a fuller picture would take significant effort.
- I could gather most relevant information with a reasonable amount of preparation.
- I am prepared to create a complete summary and clarify any missing details needed for planning.
- I have a workable routine for reviewing accounts and handling important tasks.
- I keep up with essentials, although larger planning projects can take longer than intended.
- Important reviews or decisions frequently pile up because other priorities take over.
- I currently have very little capacity for financial coordination, and significant choices remain open.
- I prefer to manage things myself and am not currently interested in paying for advice.
- I might pay a fixed amount for a focused question or one-time review.
- I would consider a project or periodic service if the scope, cost, and value were transparent.
- I have room for ongoing advice if the service addresses needs I consider important.
Do I Need a Financial Advisor Quiz - Description and methodology of the test
People considering professional money guidance can use the Do I Need a Financial Advisor Quiz to organize a practical decision before contacting a provider. It is intended for people reviewing their own finances, whether they feel confident managing them or face competing goals, complex arrangements, limited time, or uncertainty about important choices. The result offers a structured financial advisor assessment rather than a recommendation of any particular firm.
What This Assessment Explores
Taken as a financial planning self-assessment, the questionnaire examines your readiness to engage with advice, how much coordination your circumstances require, and where decisions become difficult. Its scenarios cover records, time, fees, advisor roles, retirement, investments, taxes, household choices, and major life changes. The three result dimensions are:
- Advisor Engagement Fit (0-15) shows readiness to collaborate, share information, assess providers, and pay for suitable help; it does not establish that advice is necessary or that a particular provider is suitable: Self-directed preference (0-5), Conditional fit (6-10), or Ready to explore (11-15).
- Financial Complexity and Coordination (0-15) reflects interconnected accounts, obligations, ownership, taxes, and goals: Streamlined finances (0-5), Growing coordination (6-10), or High coordination load (11-15).
- Financial Decision-Support Need (0-15) indicates how manageable consequential choices feel: Independent momentum (0-5), Selective support (6-10), or Strong support case (11-15).
Methodology and Evidence Base
Each item presents a financial situation with four response choices, generally moving from independence or simplicity toward greater coordination, support, or advisor involvement. The questions ask how you would act and how difficult a decision feels. Responses produce the displayed scores and named bands, but the questionnaire does not specify point-by-point weighting, so exact answer values should not be inferred.
The closest conceptual reference is Lown and Cook’s Financial Counseling Attitude Scale, which addresses attitudes toward seeking counseling. This questionnaire is conceptually consistent with that work, not an adaptation of it. Work by Gerrans and Hershey adds context on advice-seeking anxiety and financial literacy; research by Stawski, Hershey, and Jacobs-Lawson connects goal clarity and planning activity with financial decisions.
The coordination and decision-support dimensions are unvalidated self-report reflections; the resulting profile helps readers clarify their financial advice needs and frame questions about whether professional guidance would be useful. Current stress, time, household circumstances, and self-perception can affect scores, so use the profile when checking credentials, fees, conflicts, services, and regulatory status.
- Lown, Jean M., and Janeen Cook. (1990). Attitudes Toward Seeking Financial Counseling: Instrument Development. Financial Counseling and Planning, 1, 93-112.
- Gerrans, Paul, and Douglas A. Hershey. (2017). Financial Adviser Anxiety, Financial Literacy, and Financial Advice Seeking. Journal of Consumer Affairs, 51(1), 54-90. 10.1111/joca.12120
- Stawski, Robert S., Douglas A. Hershey, and Joy M. Jacobs-Lawson. (2007). Goal Clarity and Financial Planning Activities as Determinants of Retirement Savings Contributions. International Journal of Aging and Human Development, 64(1), 13-32. 10.2190/13GK-5H72-H324-16P2
Updated: